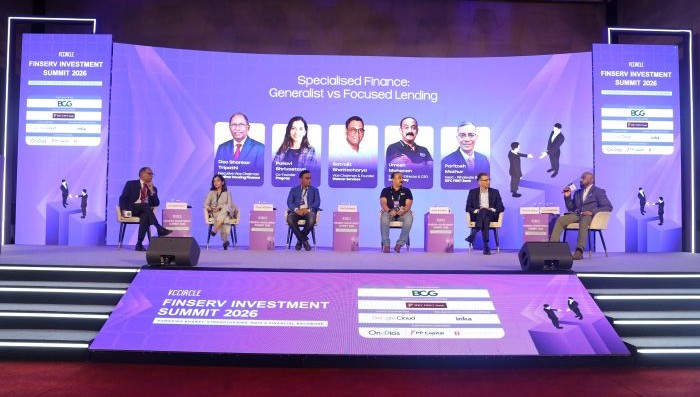
Lenders should diversify their operations only if it adds value to the organisation and not just to derisk their portfolio, otherwise they should focus on specialisation for better underwriting and resultant resilience through economic cycles, according to panelists at the VCCircle Finserv Investment Summit 2026.
“When it does not add the value, diversification is simply a myth and it will destroy [the core business],” Aadhar Housing Finance executive vice chairman Deo Shankar Tripathi said.
The panel also included Progcap co-founder Pallavi Shrivastava; Indel Money executive director and chief executive officer Umesh Mohanan; Weaver Services vice chairman and founder Satrajit Bhattacharya; and IDFC First Bank wholesale-banking head Paritosh Mathur.
Broadly, as the panelists noted, lenders tend to diversify their operations for various reasons including need to reduce dependence on a particular product or geography, paucity of demand in a specific market and shrinking margins.
However, they added that this strategy should not be followed blindly.
Weaver’s Bhattacharya noted that diversification should ideally be done with the intention of solving a problem. It should not be “a strategy in search of a problem to solve.”
Panelists emphasised the need for lenders to specialise on a specific product.
“I am a supporter of specialisation," said Indel Money's Mohanan, explaining that this allows you to align the business' fortunes with a long-term economic growth story rather than with cyclical hype.
Mohanan added that specialisation helps create a robust underwriting system for a particular product and also helps cater to underserved segments. This is both integral to financial inclusion and helpful to improve margins.
According to the Reserve Bank of India’s norms, a housing finance company must maintain atleast 50% of its net assets as qualifying housing finance assets. Similarly, the qualifying assets of NBFC-MFIs shall constitute a minimum of 60% of the entity’s total assets.
Many non-bank lenders have sought to specifically cater to the micro, small and medium-enterprise (MSME) segment.
Targeted service
Progcap's Shrivastava said that nine years in the field have taught them that MSME lending is a specialised field. "I fundamentally believe we can address a huge credit cap in our economy if we are trying to address the demand of specific customer segments,” Shrivastava added.
Lastly, IDFC First Bank’s Mathur acknowledged that while credit rating agencies favour lenders with diverse portfolios, having a sustainable underwriting model is equally important.
“We will welcome an entity (NBFC borrower) with open doors even if it is triple C rated, as long as we trust the company’s underwriting philosophy and the model it is using,” Mathur said.
“Would we prefer diversified lenders? Yes. But my definition of diversity is not necessarily about adjacency of the product, but diversity of the client base too,” he added.